Milan Adams
Cashless Society, Economy, Preppers
When Money Stops Being Money
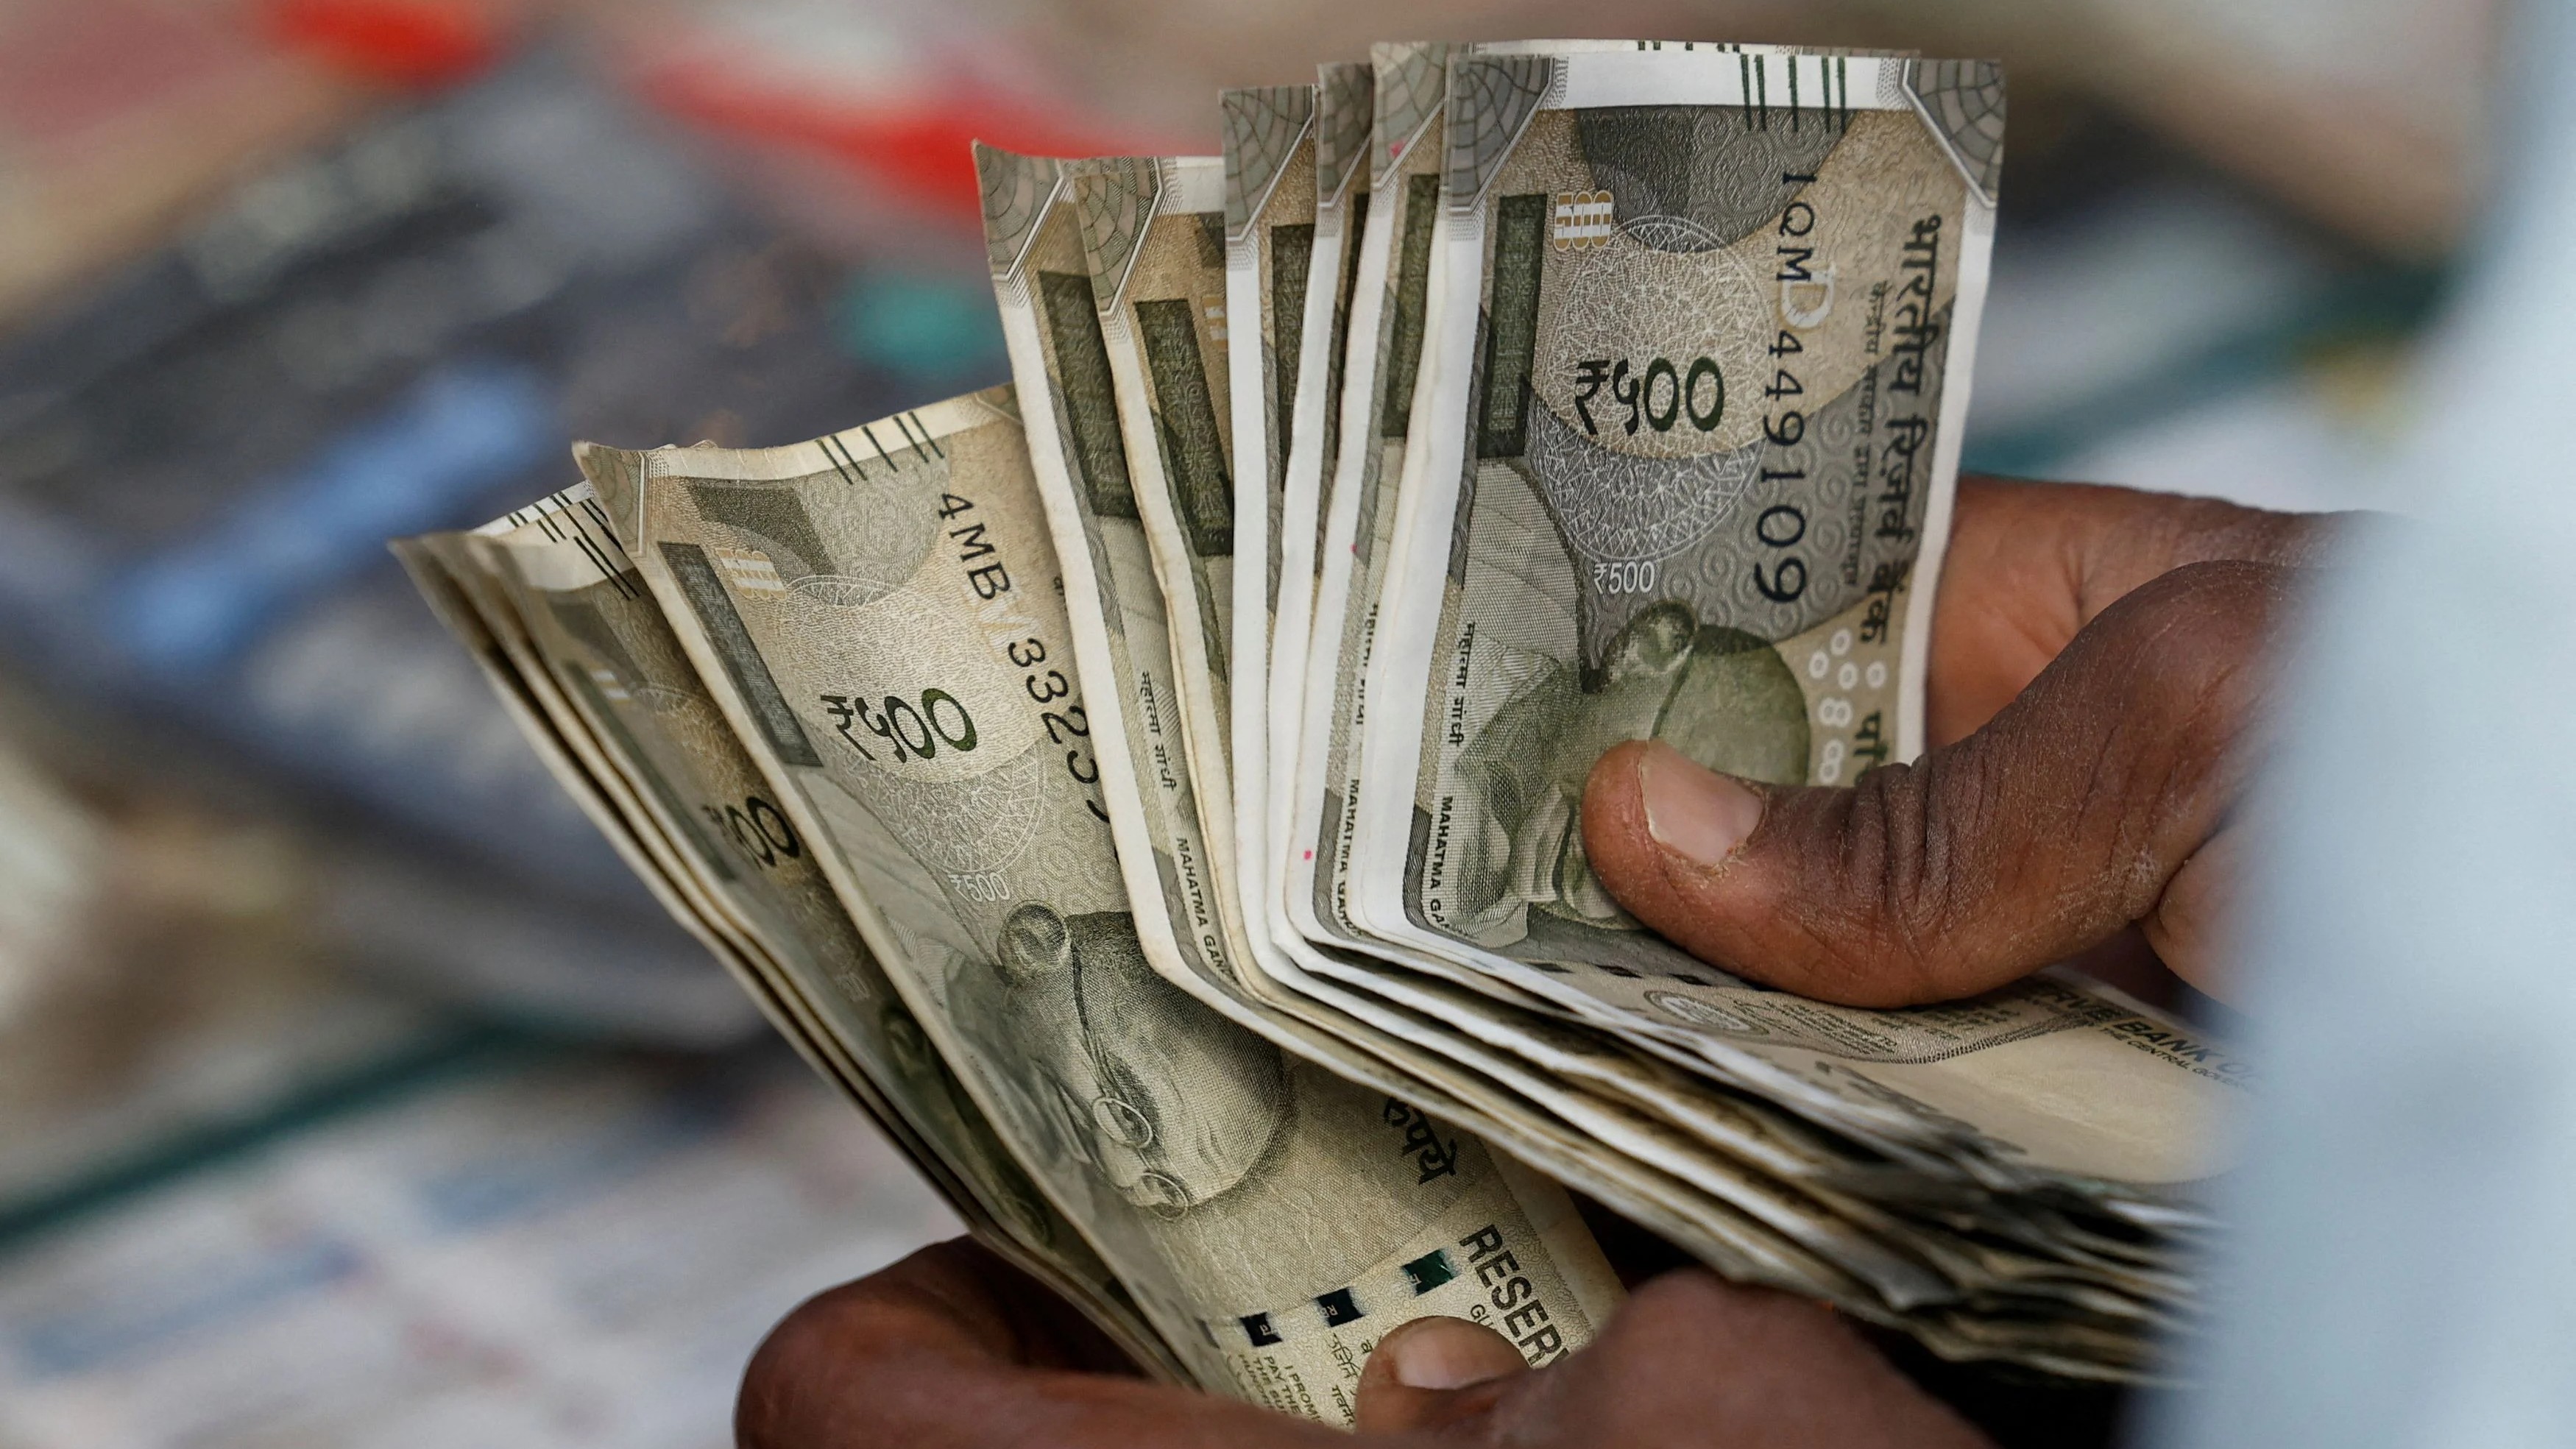
Something fundamental is vanishing, and most people will not notice until it is already gone. Not with a declaration. Not with a law passed in the dead of night. Simply, gradually, the option to buy something without creating a permanent record will disappear. The ability to save purchasing power outside of a system that can freeze it, monitor it, or program it will become a memory that seems almost fictional to those who never experienced it.
I have watched this unfold over years of observing payment systems, reading central bank white papers that few citizens bother to examine, and noticing how my own transactions leave increasingly detailed trails. The pattern is consistent across nations: convenience precedes surveillance, and surveillance precedes control.
We are not approaching a cashless society. We are sleepwalking into it. And for anyone who values independence, privacy, or the basic human right to conduct commerce without surveillance, this represents not progress but regression toward a form of control that previous generations would have recognized immediately and resisted forcefully.
Central Bank Digital Currencies (CBDCs) are the mechanism of this transformation. The digital euro, the potential digital dollar, the digital yuan already operational in China—these are not simply modernizations of payment systems. They are structural changes to the relationship between the individual and the state, between commerce and surveillance, between freedom and permission. Once fully implemented, they would create a financial infrastructure where every transaction is visible, every purchase is logged, and every economic decision requires implicit or explicit approval from authorities.
This is not speculation. This is documented policy. The Bank for International Settlements, which coordinates central banking globally, has explicitly stated that CBDCs will enable “programmable money”—currency that can be restricted based on time, place, or purpose. The European Central Bank’s digital euro project includes provisions for offline payments only up to limited amounts, with all larger transactions requiring network connectivity and identity verification. The Federal Reserve’s FedNow system, launched in July 2023, created the technical infrastructure for instant digital payments that serves as the foundation for eventual CBDC implementation.
September 26, 2026
When Money Stops Being Money
Something fundamental is vanishing, and most people will not notice until it is already gone. Not with a declaration. Not with a law passed in the dead of night. Simply, gradually, the option to buy something without creating a permanent record will disappear. The ability to save purchasing power outside of a system that can freeze it, monitor it, or program it will become a memory that seems almost fictional to those who never experienced it.
I have watched this unfold over years of observing payment systems, reading central bank white papers that few citizens bother to examine, and noticing how my own transactions leave increasingly detailed trails. The pattern is consistent across nations: convenience precedes surveillance, and surveillance precedes control.
We are not approaching a cashless society. We are sleepwalking into it. And for anyone who values independence, privacy, or the basic human right to conduct commerce without surveillance, this represents not progress but regression toward a form of control that previous generations would have recognized immediately and resisted forcefully.
Central Bank Digital Currencies (CBDCs) are the mechanism of this transformation. The digital euro, the potential digital dollar, the digital yuan already operational in China—these are not simply modernizations of payment systems. They are structural changes to the relationship between the individual and the state, between commerce and surveillance, between freedom and permission. Once fully implemented, they would create a financial infrastructure where every transaction is visible, every purchase is logged, and every economic decision requires implicit or explicit approval from authorities.
This is not speculation. This is documented policy. The Bank for International Settlements, which coordinates central banking globally, has explicitly stated that CBDCs will enable “programmable money”—currency that can be restricted based on time, place, or purpose. The European Central Bank’s digital euro project includes provisions for offline payments only up to limited amounts, with all larger transactions requiring network connectivity and identity verification. The Federal Reserve’s FedNow system, launched in July 2023, created the technical infrastructure for instant digital payments that serves as the foundation for eventual CBDC implementation.