Showing posts with label income. Show all posts

Tuesday, October 20, 2026

$32 million CEO lectures America on income inequality


Published October 19, 2026 12:13pm EDT

Scott Kirby also defended charging passengers more for certain seating options


By Bradford Betz FOXBusiness

United Airlines CEO wealth tax proposal blasted as double taxation

Dagen McDowell slams United Airlines CEO Scott Kirby over his proposal for a national wealth tax and a near-100% inheritance tax. She calls out the double taxation and points to the hypocrisy of the airline's own elite status pricing.

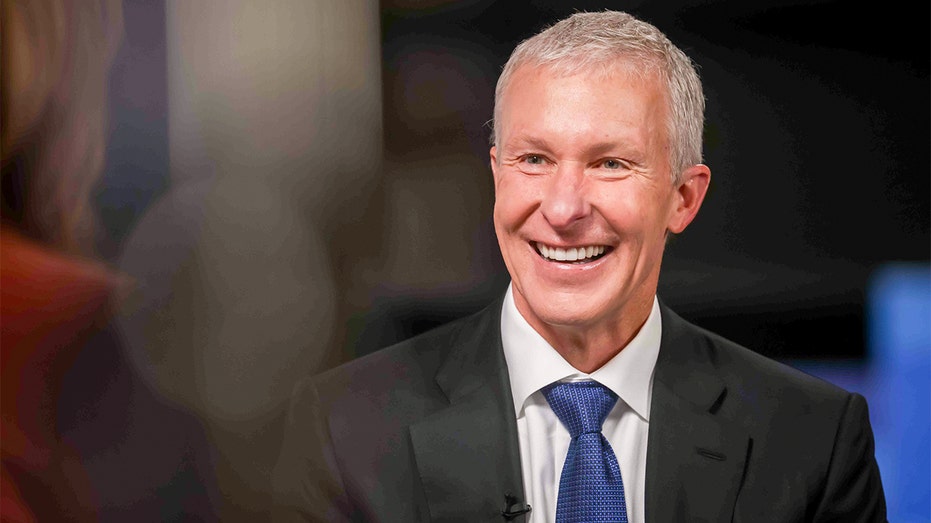
United Airlines CEO Scott Kirby is calling for a national wealth tax and inheritance taxes approaching 100% for certain estates, arguing that growing wealth inequality poses a threat to American society.

Kirby, who took home about $32.3 million in total compensation in fiscal year 2025, made the remarks when asked about declining public trust in corporate executives during an interview with The New York Times.

"Wealth inequality has become a danger to our society, and we need to address that," Kirby told the outlet in an interview published Sunday.


United Airlines CEO Scott Kirby is calling for a national wealth tax and inheritance taxes approaching 100% for certain estates. (Michael Nagle/Bloomberg via Getty Images)

The airline executive argued that a wealth tax would need to be implemented nationwide rather than at the state level to prevent wealthy Americans from relocating to avoid paying it.

Monday, September 11, 2017

Guaranteed paychecks? Advocates push universal basic income


Guaranteed paychecks? Advocates push universal basic income


Driverless trucks. Factory robots. Delivery drones. Virtual personal assistants. As technological innovations increasingly edge into the workplace, many people fear that robots and machines are destined to take jobs …


Sunday, February 21, 2016

The US Economy Has Not Recovered and Will Not Recover


PAUL CRAIG ROBERTS
• FEBRUARY 17, 2016


Lisa S. / Shutterstock.com


The US economy died when middle class jobs were offshored and when the financial system was deregulated.

Jobs offshoring benefitted Wall Street, corporate executives, and shareholders, because lower labor and compliance costs resulted in higher profits. These profits flowed through to shareholders in the form of capital gains and to executives in the form of “performance bonuses.” Wall Street benefitted from the bull market generated by higher profits.

However, jobs offshoring also offshored US GDP and consumer purchasing power. Despite promises of a “New Economy” and better jobs, the replacement jobs have been increasingly part-time, lowly-paid jobs in domestic services, such as retail clerks, waitresses and bartenders.

The offshoring of US manufacturing and professional service jobs to Asia stopped the growth of consumer demand in the US, decimated the middle class, and left insufficient employment for college graduates to be able to service their student loans. The ladders of upward mobility that had made the United States an “opportunity society” were taken down in the interest of higher short-term profits.

Without growth in consumer incomes to drive the economy, the Federal Reserve under Alan Greenspan substituted the growth in consumer debt to take the place of the missing growth in consumer income. Under the Greenspan regime, Americans’ stagnant and declining incomes were augmented with the ability to spend on credit. One source of this credit was the rise in housing prices that the Federal Reserves low inerest rate policy made possible. Consumers could refinance their now higher-valued home at lower interest rates and take out the “equity” and spend it.

The debt expansion, tied heavily to housing mortgages, came to a halt when the fraud perpetrated by a deregulated financial system crashed the real estate and stock markets. The bailout of the guilty imposed further costs on the very people that the guilty had victimized.

Under Fed chairman Bernanke the economy was kept going with Quantitative Easing, a massive increase in the money supply in order to bail out the “banks too big to fail.” Liquidity supplied by the Federal Reserve found its way into stock and bond prices and made those invested in these financial instruments richer. Corporate executives helped to boost the stock market by using the companies’ profits and by taking out loans in order to buy back the companies’ stocks, thus further expanding debt.

Those few benefitting from inflated financial asset prices produced by Quantitative Easing and buy-backs are a much smaller percentage of the population than was affected by the Greenspan consumer credit expansion. A relatively few rich people are an insufficient number to drive the economy.

The Federal Reserve’s zero interest rate policy was designed to support the balance sheets of the mega-banks and denied Americans interest income on their savings. This policy decreased the incomes of retirees and forced the elderly to reduce their consumption and/or draw down their savings more rapidly, leaving no safety net for heirs.

Using the smoke and mirrors of under-reported inflation and unemployment, the US government kept alive the appearance of economic recovery. Foreigners fooled by the deception continue to support the US dollar by holding US financial instruments.

The official inflation measures were “reformed” during the Clinton era in order to dramatically understate inflation. The measures do this in two ways. One way is to discard from the weighted basket of goods that comprises the inflation index those goods whose price rises. In their place, inferior lower-priced goods are substituted.

For example, if the price of New York strip steak rises, round steak is substituted in its place. The former official inflation index measured the cost of a constant standard of living. The “reformed” index measures the cost of a falling standard of living.

The other way the “reformed” measure of inflation understates the cost of living is to discard price rises as “quality improvements.” It is true that quality improvements can result in higher prices. However, it is still a price rise for the consumer as the former product is no longer available. Moreover, not all price rises are quality improvements; yet many prices rises that are not can be misinterpreted as “quality improvements.”

These two “reforms” resulted in no reported inflation and a halt to cost-of-living adjustments for Social Security recipients. The fall in Social Security real incomes also negatively impacted aggregate consumer demand.

The rigged understatement of inflation deceived people into believing that the US economy was in recovery. The lower the measure of inflation, the higher is real GDP when nominal GDP is deflated by the inflation measure. By understating inflation, the US government has overstated GDP growth.

What I have written is easily ascertained and proven; yet the financial press does not question the propaganda that sustains the psychology that the US economy is sound. This carefully cultivated psychology keeps the rest of the world invested in dollars, thus sustaining the House of Cards.

John Maynard Keynes understood that the Great Depression was the product of an insufficiency of consumer demand to take off the shelves the goods produced by industry. The post-WW II macroeconomic policy focused on maintaining the adequacy of aggregate demand in order to avoid high unemployment. The supply-side policy of President Reagan successfully corrected a defect in Keynesian macroeconomic policy and kept the US economy functioning without the “stagflation” from worsening “Philips Curve” trade-offs between inflation and employent. In the 21st century, jobs offshoring has depleted consumer demand’s ability to maintain US full employment.

The unemployment measure that the presstitute press reports is meaningless as it counts no discouraged workers, and discouraged workers are a huge part of American unemployment. The reported unemployment rate is about 5%, which is the U-3 measure that does not count as unemployed workers who are too discouraged to continue searching for jobs.

The US government has a second official unemployment measure, U-6, that counts workers discouraged for less than one-year. This official rate of unemployment is 10%.

When long term (more than one year) discouraged workers are included in the measure of unemployment, as once was done, the US unemployment rate is 23%. (See John Williams, shadowstats.com)

Fiscal and monetary stimulus can pull the unemployed back to work if jobs for them still exist domestically. But if the jobs have been sent offshore, monetary and fiscal policy cannot work.

What jobs offshoring does is to give away US GDP to the countries to which US corporations move the jobs. In other words, with the jobs go American careers, consumer purchasing power and the tax base of state, local, and federal governments. There are only a few American winners, and they are the shareholders of the companies that offshored the jobs and the executives of the companies who receive multi-million dollar “performance bonuses” for raising profits by lowering labor costs. And, of course, the economists, who get grants, speaking engagements, and corporate board memberships for shilling for the offshoring policy that worsens the distribution of income and wealth. An economy run for a few only benefits the few, and the few, no matter how large their incomes, cannot consume enough to keep the economy growing.

In the 21st century US economic policy has destroyed the ability of real aggregate demand in the US to increase. Economists will deny this, because they are shills for globalism and jobs offshoring. They misrepresent jobs offshoring as free trade and, as in their ideology free trade benefits everyone, claim that America is benefitting from jobs offshoring. Yet, they cannot show any evidence whatsoever of these alleged benefits. (See my book, The Failure of Laissez Faire Capitalism and Economic Dissolution of the West.) http://www.amazon.com/Failure-Laissez-Faire-Capitalism/dp/0986036250/ref=sr_1_1?s=books&ie=UTF8&qid=1455746560&sr=1-1&keywords=paul+craig+roberts-the+failure+of+laissez-faire+capitalism

As an economist, it is a mystery to me how any economist can think that a population that does not produce the larger part of the goods that it consumes can afford to purchase the goods that it consumes. Where does the income come from to pay for imports when imports are swollen by the products of offshored production?

We were told that the income would come from better-paid replacement jobs provided by the “New Economy,” but neither the payroll jobs reports nor the US Labor Departments’s projections of future jobs show any sign of this mythical “New Economy.”

There is no “New Economy.” The “New Economy” is like the neoconservatives promise that the Iraq war would be a six-week “cake walk” paid for by Iraqi oil revenues, not a $3 trillion dollar expense to American taxpayers (according to Joseph Stiglitz and Linda Bilmes) and a war that has lasted the entirely of the 21st century to date, and is getting more dangerous.

The American “New Economy” is the American Third World economy in which the only jobs created are low productivity, low paid nontradable domestic service jobs incapable of producing export earnings with which to pay for the goods and services produced offshore for US consumption.

The massive debt arising from Washington’s endless wars for neoconservative hegemony now threaten Social Security and the entirety of the social safety net. The presstitute media are blaming not the policy that has devasted Americans, but, instead, the Americans who have been devasted by the policy.

Earlier this month I posted readers’ reports on the dismal job situation in Ohio, Southern Illinois, and Texas. In the March issue of Chronicles, Wayne Allensworth describes America’s declining rural towns and once great industrial cities as consequences of “globalizing capitalism.” A thin layer of very rich people rule over those “who have been left behind”—a shrinking middle class and a growing underclass. According to a poll last autumn, 53 percent of Americans say that they feel like a stranger in their own country.

Most certainly these Americans have no political representation. As Republicans and Democrats work to raise the retirement age in order to reduce Social Security outlays, Princeton University experts report that the mortality rates for the white working class are rising. The US government will not be happy until no one lives long enough to collect Social Security.

The United States government has abandoned everyone except the rich.

In the opening sentence of this article, I said that the two murderers of the American economy were jobs offshoring and financial deregulation. Deregulation greatly enhanced the ability of the large banks to financialize the economy. Financialization is the diversion of income streams into debt service. When debt service absorbs a large amount of the available income, the economy experiences debt deflation. The service of debt leaves too little income for purchases of goods and services and prices fall.

Michael Hudson, who I recently wrote about, is the expert on finanialization. His book,Killing the Host, which I recommended to you, tells the complete story. Briefly, financialization is the process by which creditors capitalize an economy’s economic surplus into interest payments to themselves. Perhaps an example would be a corporation that goes into debt in order to buy back its shares. The corporation achieves a temporary boost in its share prices at the cost of years of interest payments that drain the corporation of profits and deflate its share price.

Michael Hudson stresses the conversion of the rental value of real estate into mortgage payments. He emphasizes that classical economists wanted to base taxation not on production, but on economic rent. Economic rent is value due to location or to a monopoly position. For example, beachfront property has a higher price because of location. The difference in value between beachfront and nonbeachfront property is economic rent, not a produced value. An unregulated monopoly can charge a price for a service that is higher than the price that would bring that service unto the market.

The proposal to tax economic rent does not mean taxing you on the rent that you pay your landlord or taxing your landlord on the rent that you pay him such that he ceases to provide the housing. By economic rent Hudson means, for example, the rise in land values due to public infrastructure projects such as roads and subway systems. The rise in the value of land opened by a new road and housing and in commercial space along a new subway line is not due to any action of the property owners. This rise in value could be taxed in order to pay for the project instead of taxing the income of the population in general. Instead, the rise in land values raises appraisals and the amount that creditors are willing to lend on the property. New purchasers and existing owners can borrow more on the property, and the larger mortgages divert the increased land valuation into interest payments to creditors. Lenders end up as the major beneficiaries of public projects that raise real estate prices.

Similarly, unless the economy is financialized to such an extent that mortgage debt can no longer be serviced, when central banks lower interest rates property values rise, and this rise can be capitalized into a larger mortgage.

Another example would be property tax reductions and legislation such as California’s Proposition 13 that freeze in whole or part the property tax base. The rise in real estate values that escape taxation are capitalized into larger mortgages. New buyers do not benefit. The beneficiaries are the lenders who capture the rise in real estate prices in interest payments.

Taxing economic rent would prevent the financial system from capitalizing the rent into debt instruments that pay interest to the financial sector. Considering the amount of rents available to be taxed, taxing rents would free production from income and sales taxation, thus lowering consumer prices and freeing labor and productive capital from taxation.

With so much of land rent already capitalized into debt instruments shifting the tax burden to economic rent would be challenging. Nevertheless, Hudson’s analysis shows that financialization, not wage suppression, is the main instrument of exploitation and takes place via the financial system’s conversion of income streams into interest payments on debt.

I remember when mortgage service was restricted to one-quarter of household income. Today mortgage service can eat up half of household income. This extraordinary growth crowds out the production of goods and services as less of household income is available for other purchases.

Michael Hudson and I bring a total indictment of the neoliberal economics profession, “junk economists” as Hudson calls them.
(Reprinted from PaulCraigRoberts.org by permission of author or representative).


.

Saturday, March 29, 2014

The Pope And Obama Share A Knack For Inspiring The Young


by Don Gonyea
March 29, 2014 8:00 AM

Listen to the Story
Morning Edition Weekend Saturday

3 min 51 sec


President Obama met with Pope Francis this week at the Vatican. Among those watching most closely were young American Catholics.


Source
.

Monday, August 19, 2013

USCCB blog criticizes income inequality, Austrian School of economics


CWN - August 19, 2013


From Our Store: Essays in Apologetics, Volume III (eBook)


Writing for the blog of the United States Conference of Catholic Bishops, a priest who serves as a labor union official linked “rampant” income inequality to the Austrian School of economics.

After citing Popes Benedict’s criticism of “unregulated capitalism” and Pope Francis’s criticism of “ideologies which uphold the absolute autonomy of the markets and financial speculation,” Father Clete Kiley said that this economic philosophy, borne [sic] of the Austrian School of Economics, is at the heart of this income gap. Pius XI called this philosophy “the poisoned spring.” In this philosophy, no one cares about income gaps; after all, it’s all about me. Implementing unregulated free market capitalism necessarily means rolling back safety regulations, outsourcing jobs, cutting back hours, bringing in immigrant guest workers without labor protections, eliminating entitlements and mounting a coordinated effort to break labor unions.

Father Kiley serves as director for immigration policy at UNITE HERE, a labor union formed in 2004 that has 265,000 members.


Additional sources for this story
Some links will take you to other sites, in a new window.


Labor Day Reflection: Income Inequality, Labor Unions and a Call to Vigilance (USCCB Blog)
UNITE HERE (Wikipedia)


Source
.
.

Sunday, August 18, 2013

Bishop Blaire Calls On Businesses, Churches, Unions, Private Citizens To Reduce Inequality In 2013 Labor Day Statement


August 12, 2013


Cites rampant income inequality in the midst of uneven economic recovery 
Urges bold action to create just economy with jobs that provide living wage
Calls for increased minimum wage, immigration reform, end to wage theft


WASHINGTON—The growing disparity in the income of U.S. workers is the focus of the 2013 Labor Day Statement of Bishop of Stockton, California, chairman of the Committee on Domestic Justice and Human Development of the U.S. Conference of Catholic Bishops (USCCB).

In the statement, dated September 2, Bishop Blaire said that most people want to live in a more equal society that provides opportunities for everyone. "The current imbalances do not have to be inevitable," Bishop Blaire wrote. "We must be bold in promoting a just economy that reduces inequality by creating jobs that pay a living wage and share with workers some profits of the company, as well as ensuring a strong safety net for jobless workers and their families and those who are incapable of work."

Bishop Blaire echoed the words of Pope Francis, that "work is fundamental to the dignity of a person…. it gives us the ability to maintain oneself, one's family, to contribute to the growth of one's own nation." Bishop Blaire said millions of workers are "denied this honor and respect as a result of unemployment, underemployment, unjust wages, wage theft, abuse or exploitation."

Even amid a modest economic recovery, he said, "Over four million people have been jobless for over six months, and that does not include the millions more who have simply lost hope; for every available job, there are as many as five unemployed and underemployed people actively vying for it. This gap pushes wages down – half of the jobs in this country pay less than $27,000. Over 46 million people live in poverty, 16 million of them children," he wrote.

He noted that individuals, the Church, businesses, government and community organizations all share the responsibility to create jobs that allow workers to support themselves and their families.

"Ethical and moral business leaders know that it is wrong to chase profits and success at the expense of workers' dignity," he wrote. "They know they have a vocation to build the kind of solidarity that honors the worker and the least among us. They remember that the economy is 'for people.'"

Bishop Blaire cited the importance of unions in helping workers participate in company decisions that affect them and noted that the rise in income inequality has paralleled the decline of unions in the United States. He urged unions to continually improve themselves and focus on issues including "raising the minimum wage, stopping wage theft," and "standing up for safe and healthy working conditions."

Bishop Blaire also voiced support for immigrants, calling for policies that "bring immigrant workers out of the shadows to a legal status and offer them a just and fair path to citizenship, so that their human rights are protected and the wages for all workers rise."

The 2013 Labor Day Statement is available online in English and Spanish at: www.usccb.org/issues-and-action/human-life-and-dignity/labor-employment/labor-day-archives.cfm

---

Keywords: Labor Day, Bishop Stephen E. Blaire, Stockton, California, Committee on Domestic Justice and Human Development, USCCB, U.S. bishops, U.S. Conference of Catholic Bishops, unemployment, underemployment, income inequality, wage theft, workers, unions, businesses, economy, minimum wage, recession, human dignity, Pope Francis

# # # # #
MEDIA CONTACT ONLY:
Don Clemmer
O: 202-541-3206


Source
.

Monday, May 20, 2013

Plutocrats: The Rise of the New Global Super-Rich and the Fall of Everyone Else


Chrystia Freeland
Reviewed by Richard N. Cooper
May/June 2013
Article Summary and Author Biography


Freeland, a journalist and editor at Thomson Reuters, examines how a fairly diverse new class of plutocrats came to be and explores some of the consequences and potential implications of its rise.


AUTHOR
PUBLISHER
Penguin Press HC, The
YEAR
2012
PAGES
336 pp.
ISBN
1594204098
PRICE
$27.95


Income and wealth in the United States today are less evenly distributed than at any time since the 1920s. One result is the emergence of a new class of plutocrats. The phenomenon is not limited to the United States: China, India, Mexico, Russia, the United Kingdom, and other states have witnessed similar changes. Freeland, a journalist and editor at Thomson Reuters, examines how this fairly diverse new class came to be and explores some of the consequences and potential implications of its rise. In a world of mass consumption, successful innovations can result in great wealth, as can any rapid social and political change, at least for those well placed or lucky enough to take advantage of new opportunities. More ominous, individuals can become fabulously wealthy at the expense of other citizens, by securing privileges from powerful government officials -- sometimes through influencing the decision-making process, sometimes through outright bribes or offers of lucrative future employment. Freeland worries about the increasing political influence of the superrich and the growing social distance between them and ordinary people. But she has surprisingly little to say about the most traditional route to plutocratic status: inherited wealth.


.

Monday, August 27, 2012

REPORT: Almost Every Household Is Worse Off Now Than It Was Three Years Ago


family

flickr via


As the economy sputters along, consumers are feeling the squeeze in their annual paychecks.

That's according to Sentier Research, whose latest report found household incomes have been declining ever since the recovery began in June 2009.

The numbers are striking: Yearly household income dwindled by 4.8 percent between June 2009 and 2012 from $53,508 to $50,964, although several types of households fared much worse than that.

"Based on our data, almost every group is worse off now than it was three years ago, with the exception of households with householders 65-years-old and over," said researcher Gordon Green.

We took a closer look at the report to see who's falling behind:

Non-family households: This group saw its real median annual income decline by 7.5 percent, from $33,002 to $30,512. Family households declined a little less than that by 4.7 percent.

Single households: Men living alone saw their real median income drop by 9.4 percent, while women's dropped by 4.5 percent.

Black households: Compared to white and Hispanic households, Black householders' income declined the most by 11.1 percent, from $35,567 to $32,498.

Householders without a college degree: People with some education but no degree saw their real median annual income slide by 9.3 percent, from $50,948 to $46,200. Associates degree holders saw theirs taper off by 8.6 percent, from $60,602 to $55,374.

Self-employed households: This group's annual income fell 9.4 percent, from $73,695 to $66,752. Private sector workers fared only a little bit better, with a decline of 4.5 percent.

Households in the West: In contrast to households in the Midwest region which barely saw a decline, households in the West felt their yearly incomes decrease by 8.5 percent, from $59,065 to $54,071.

Households with householders between 55 and 66: Compared to millennials who saw their real median household income drop 8.9 percent, boomers' declined by 9.7 percent, from $61,716 to $55,748.

In a surprising twist, householders between 65 and 74-years-old got a boost in their income by 6.5 percent.


Source:
http://www.businessinsider.com/report-almost-every-group-is-worse-off-now-than-it-was-three-years-ago-2012-8#ixzz24m5PMj00
.

Monday, June 11, 2012

Family Net Worth Drops to Level of Early ’90s, Fed Says

By BINYAMIN APPELBAUM

Published: June 11, 2012

WASHINGTON — The recent economic crisis left the median American family in 2010 with no more wealth than in the early 1990s, erasing almost two decades of accumulated prosperity, the Federal Reserve said Monday.


Andrew Harrer/Bloomberg News

A house for sale in Washington. Falling home prices accounted for three-quarters of the losses in net worth.


A hypothetical family richer than half the nation’s families and poorer than the other half had a net worth of $77,300 in 2010, compared with $126,400 in 2007, the Fed said. The crash of housing prices directly accounted for three-quarters of the loss.

Families’ income also continued to decline, a trend that predated the crisis but accelerated over the same period. Median family income fell to $45,800 in 2010 from $49,600 in 2007. All figures were adjusted for inflation.

The new data comes from the Fed’s much-anticipated release on Monday of its Survey of Consumer Finances, a report issued every three years that is one of the broadest and deepest sources of information about the financial health of American families.

While the numbers are already 18 months old, the survey illuminates problems that continue to slow the pace of the economic recovery. The Fed found that middle-class families had sustained the largest percentage losses in both wealth and income during the crisis, limiting their ability and willingness to spend.

“It fills in details to a picture that we already knew was quite ugly, and these details very much underscore that,” said Jared Bernstein, an economist at the Center on Budget and Policy Priorities who served as an adviser to Vice President Joseph R. Biden Jr. “It makes clear how devastating this has been for the middle class.”

Given the scale of those losses, consumer spending has remained surprisingly resilient. The survey also illuminates where the money is coming from: American families saved less and only slowly repaid debts.

The share of families saving anything over the previous year fell to 52 percent in 2010 from 56.4 percent in 2007. Other government statistics show that total savings have increased since 2007, suggesting that a smaller group of families is saving more money, while a growing number manage to save nothing.

The survey also found a shift in the reasons that families set aside money, underscoring the lack of confidence that is weighing on the economy. More families said they were saving money as a precautionary measure, to make sure they had enough liquidity to meet short-term needs. Fewer said they were saving for retirement, or for education, or for a down payment on a home.

The report underscored the limited progress that households had made in reducing the amounts that they owed to lenders. The share of households reporting any debt declined by 2.1 percentage points over the last three years, but 74.9 percent of households still owed something, and the median amount did not change.

The decline in reported incomes could have increased the weight of those debts, tying up a larger share of families’ take-home pay. But one of the rare benefits of the crisis, historically lower interest rates, has helped to offset that effect. Families also have been able to reduce debt payments by refinancing into mortgages with longer terms and deferring repayment of student loans and other obligations.

The survey also confirmed that Americans are shifting the kinds of debts they carry. The share of families with credit card debt declined by 6.7 percentage points to 39.4 percent, and the median balance fell 16.1 percent to $2,600.

Families also reduced the number of credit cards that they carried, and 32 percent of families said they had no cards, up from 27 percent in 2007.

Conversely, the share of families with education-related debt rose to 19.2 percent in 2010 from 15.2 percent in 2007. The Fed noted that education loans made up a larger share of the average family’s obligations than loans to buy automobiles for the first time in the history of the survey.

The cumulative statistics concealed large disparities in the impact of the crisis.

Families with incomes in the middle 60 percent of the population lost a larger share of their wealth over the three-year period than the wealthiest and poorest families.

One basic reason for this disproportion is that the wealth of the middle class is mostly in housing, and the median amount of home equity dropped to $75,000 in 2010 from $110,000 in 2007. And while other forms of wealth have recovered much of the value lost in the crisis, housing prices have hardly budged.

Those middle-income families also lost a larger share of their income. The earnings of the median family in the bottom 20 percent of the income distribution actually increased from 2007 to 2010, in part because of the expansion of government aid programs during therecession. Wealthier families, which derive more income from investments, were also cushioned against the recession.

The data does provide the latest indication, however, that the recession reduced income inequality in the United States, at least temporarily. The average income of the wealthiest families fell much more sharply than the median, indicating that some of those at the very top of the ladder slipped down at least a few rungs.

Ranking American families by income, the top 10 percent of households still earned an average of $349,000 in 2010.

The average net worth of the same families was $2.9 million
.


Source