Showing posts with label Insurance. Show all posts

Sunday, September 21, 2014

How Catholic Insurance Companies Outsource Contraceptive Coverage


policy-ish


by JULIE ROVNER
September 17, 201412:02 PM ET


Contraceptive coverage has long been required by state laws or sought by nonreligious employers the religious health plans serve.iStockphoto

Catholic and other religious hospitals and universities have been arguing in federal court for much of the past two years that they shouldn't have to offer or facilitate birth control as part of their employee health plans because it violates their religious beliefs.

But what happens when the insurance company is itself Catholic? It turns out that Catholic health plans have for years been arranging for outside firms to provide contraceptive coverage to their enrollees.

That's because such coverage has long been required by state laws or sought by nonreligious employers the religious health plans serve.

The federal health law requires most health insurance plans, including all new plans in the individual and small group markets, to provide contraceptive coverage at no out-of-pocket cost to women.

That divergence between the Catholic court claim that any link to contraceptive coverage is forbidden and the actions of Catholic insurance plans is likely to draw more attention as more large Catholic hospital systems add insurance plans to their portfolios.

Already a bishop in Arkansas is raising questions about one of the insurers in his state.

No one is keeping track of just how many Catholic health plans are entering the insurance market and selling to non-Catholics. The latest entry is Catholic Health Initiatives, the nation's fifth-largest nonprofit health system, with facilities in 18 states.

Juan Serrano, who heads CHI's new insurance subsidiary, Prominence Health, said in an interview that over the next year and a half, Prominence plans to "expand our health plan footprint into additional Catholic Health Initiative markets ... where they make the most sense."

He said that "as relates to the mandated benefits that are required in the marketplace, we are taking the same position that has been taken by other Catholic health plans, and it is to cede or contract with a third-party administrator who will administer the ERD-related benefits in an arm's-length manner."

ERD refers to the Ethical and Religious Directives for Catholic Health Care, a document from the Conference of Catholic Bishops that among other things makes contraception off-limits for Catholic institutions.

While CHI's third-party strategy might please health law advocates, the bishop who heads the Diocese of Little Rock, Ark., raised a red flag when the company purchased QualChoice, its first commercial plan in that state, last spring.

"Having given this matter serious thought and prayer, I am not fully convinced by CHI's reasoning that their acquisition of QualChoice will pose no moral or ethical conflicts," Bishop Anthony Taylor said in a statement.

MergerWatch, a reproductive health advocacy group that tracks deals involving secular and religious health institutions, is keeping a close eye on Catholic plans in the commercial market.

"We're now seeing more and more of these plans moving into the commercial market in a big way," said Lois Uttley, director of the group. "Under the Affordable Care Act, these plans are supposed to be covering contraception. So they have to figure out some way to get that to their enrollees, despite their religious objections to contraception."

MergerWatch has been closely watching how Fidelis Care, a Catholic-owned insurer that this year was the second-most-popular plan on the New York state health exchange, is handling reproductive health services.

Fidelis has arranged for a third party to provide women's reproductive health services, although that's not clear on the plan's website. In its handbook for health care providers Fidelis explains it "has elected not to offer all reproductive and family planning services, including abortion, sterilization, and artificial contraception, as a standard benefit nor to receive premium dollars from the State of New York for such services."

Instead, the company "will inform these same providers that the New York State of Health Marketplace has approved Unified IPA, LLC to provide New York State of Health marketplace-mandated family planning services, independent of Fidelis Care." The online marketplace operates under the health law, offering competing plans to people who generally don't have approved employer-based coverage.

A spokeswoman for Fidelis wrote in an email that health plan members need not worry about getting special access to the outside insurer because "the process is seamless for members. Providers simply bill the outside firm."

Mike Elliott, a principal with Unified IPA, the outside firm, says he contracts with the same health care providers that Fidelis does and works with the same pharmacy benefit firms to ensure that prescriptions are filled without Fidelis having to participate.

"From the member's perspective they're getting to see the same doctor, they have the same benefit package ... and we utilize the same ID number as the health plan," said Elliott, who says he has been providing reproductive health services to religious health plans for nearly three decades.

With Fidelis, that process has not been exactly seamless, says MergerWatch. Uttley said her group called several health plans asking about contraceptive coverage, and the response from Fidelis "was particularly confusing. The customer service woman said, 'Well, Fidelis covers contraception if you need it to regulate yourself,' whatever that means. If you need it for other reasons, you have to call this IPA."

That's troublesome, said Uttley, because "that's confusing even to a sophisticated insurance consumer used to having health insurance, and what we have now coming into the marketplace is a lot of people who have never had insurance. It's enough of a challenge to get them to understand how health insurance works without having this wrinkle in it."

Another problem for the group is that Fidelis, unlike many other nonreligious health plans, refuses to allow Planned Parenthood into its network of covered providers, "not even for prenatal or primary care," Uttley said. "It's not clear to us that women enrolling in Fidelis in New York understand they can't use that coverage at a Planned Parenthood if that's been their primary source of family planning services in the past."

In Arkansas, the bishop's concerns remain unresolved. Taylor sought clarification from the Vatican, and according to diocesan spokesman Dennis Lee, "Bishop Taylor has received a substantive response from the Vatican regarding CHI's acquisition of QualChoice, and he is actively involved in ongoing, private discussions with CHI on how best to comply with the Vatican's response."

The issues are clearer to other Catholic health plans that don't have to meet the needs of non-Catholics in the commercial insurance market. They're arguing in court that any participation with the contraceptive mandate is forbidden.

The Little Sisters of the Poor religious order, which provides long-term-care services with employees insured by Christian Brothers Services, is rejecting the Obama administration's newest policy: allowing religious employers to notify the government, instead of their insurer, that they have a religious objection to providing contraceptive coverage. "Any provision of the Mandate's services through the plan ... would violate the Christian Brothers' and Little Sisters' faith," the lawyers argue.

In the case of Christian Brothers, the administration argues that because it is itself a religious plan, it is exempt from the requirements anyway.


Source
.

Monday, December 09, 2013

Looking Past Website, More Challenges Await Obamacare

7 min 48 sec
An increasing number of people are signing up for health insurance through the government's new exchange, suggesting the Obama administration has made progress in fixing its broken website. But the exchange is just one part of the health care law, which remains politically divisive almost four years after its passage.


Source

.

Monday, December 02, 2013

Supreme Court won’t hear challenge to Obamacare’s employer mandate


By Aaron Blake


December 2 at 12:22 pm


The Supreme Court opted Monday not to take up a case challenging Obamacare's requirement that most employers provide health insurance to their employees.

The court instead opted to leave in place an appeals court's ruling striking down the lawsuit, which was brought by Liberty University, an evangelical college in Virginia.

It is the second time the court has opted not to hear an appeal to the health-care law's employer mandate. The court previously declined to review the employer mandate while taking up the individual health-insurance mandate — a mandate that it eventually upheld.

The health-care law requires employers with at least 50 workers to provide basic health insurance coverage.

The 4th Circuit Court of Appeals in Richmond, Va., originally struck down Liberty's lawsuit.

"...it is simply another example of Congress’s longstanding authority to regulate employee compensation offered and paid for by employers in interstate commerce," the appeals court wrote.

The court announced last week that it will also hear a case challenging Obamacare's requirement that employers provide health insurance that includes contraception.

For more on the Supreme Court's moves today, see Robert Barnes's recap.


Source


 Related

Current U.S. Supreme Court Members

The following table lists the current members of the United States Supreme Court, including the Chief Justice and eight Associate Justices.

See Also: Past U.S. Supreme Court Members

Service Birth
Name, stateAssoc. JusticeChief JusticeYrs Place Date Died Religion
Antonin Scalia, DC 1986–N.J. 1936 Roman Catholic
Anthony M. Kennedy, Calif. 1988–Calif. 1936 Roman Catholic
Clarence Thomas, DC 1991–Ga. 1948 Roman Catholic
Ruth Bader Ginsburg, DC 1993–N.Y. 1933 Jewish
Stephen G. Breyer, Mass. 1994–Calif. 1938 Jewish
John G. Roberts, DC2005–N.Y.1955Roman Catholic
Samuel A. Alito, Jr., N.J.2006–N.J.1950Roman Catholic
Sonia Sotomayor N.Y.2009–N.Y.1954Roman Catholic
Elena Kagan N.Y.2010–N.Y.1960Jewish

.
 Source
 .

Wednesday, November 20, 2013

Obama wants to rebrand, remarket ObamaCare


By S.A. Miller

November 20, 2013 | 6:29am


Photo: Drew Angerer-Pool/Getty Images


WASHINGTON — Maybe they should get a license from Apple and call it iCare.

President Obama promised Tuesday that after fixing ObamaCare, he would “rebrand” it for resale to a skeptical American public.

“We’re obviously going to have to remarket and rebrand, and that will be challenging in this political environment,” Obama told a conference of CEOs in Washington hosted by The Wall Street Journal.

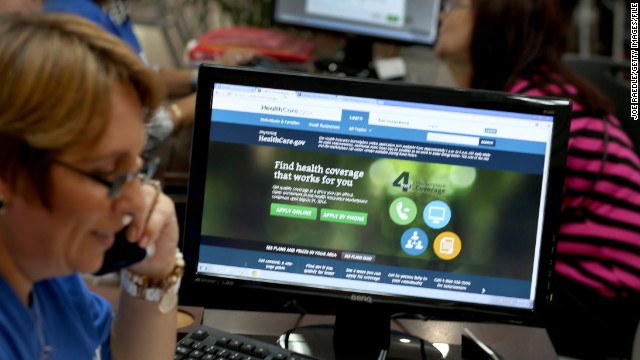
But as Obama talked about marketing strategy, more problems emerged with the glitch-plagued HealthCare.gov Web site.

A top cyber-security expert warned Congress that the site is full of holes that likely have already put Americans’ sensitive personal information at risk.

“Hackers are definitely after it,” David Kennedy, CEO of the Web-security firm TrustedSec told a House panel.

“There are just fundamental security principles that are not being followed . . . That could compromise the entire site itself and everything around it,” he said, noting it linked to the IRS, Homeland Security and the credit-reporting agency Experian.

What’s more, a top administration IT official told another House committee that about 30 percent of the Web site is still under construction.

“We still need to build the payments system to make the payments [to insurance companies] in January,” revealed Henry Chao, deputy chief information officer at the Centers for Medicare and Medicaid Services, which runs the Web site.


Source
.

Tuesday, November 05, 2013

ObamaCare architect defends plan, says president not to blame for rollout glitches


POLITICS

Published November 03, 2013
FoxNews.com

Ezekiel EmanuelFox News


WASHINGTON – The architect of the Affordable Care Act insisted on “Fox News Sunday” that President Obama isn’t to blame for the rocky rollout of ObamaCare and deflected charges that the administration misled Americans about being able to keep their current health plans.

Ezekiel Emanuel, a bioethicist, was part of the president’s health care reform team for two years and is the brother of former Obama Chief of Staff Rahm Emanuel.

“We grandfathered in plans,” Emanuel said.

Host Chris Wallace pressed Emanuel to defend the growing number of cancellation notices sent to people whose plans changed after the law was implemented, but Emanuel could not.

Instead, he blamed much of the problems on insurance companies and not the new law.

“The law does not say ‘Sears drop coverage!’ Sears decides what’s good for Sears,” Emanuel said. “The insurance decides how to make money. When the private companies decide to drop an individual, you blame Obama. He isn’t responsible for that.”

Wallace’s other guest in the segment, James Capretta of the Ethics and Public Policy Center, called the grandfather clause in ObamaCare too narrow, adding that “the whole point of the exchanges was to close down the individual insurance market.”

Capretta called out Obama’s pitch to the public about the benefits of the plan and repeated pledges that Americans would be able to keep their current insurance providers if they liked it misleading and says Obama should shoulder the blame.

“There’s no extenuating circumstances,” Capretta said. “It was central to passing the law. He said clearly you can keep your plan. This wasn’t a minor pledge. It was central to the law. He broke that pledge.”

Capretta said the Obama administration “shouldn’t be able to play fast and loose” with people’s medical coverage.

In recent days, a growing number of Democrats have joined Republicans calling to extend the March 31 deadline to sign up for health insurance. They argue that the White House should extend the deadline to make sure that people who want it have enough time to buy it.

Capretta suggested “delaying the whole thing for a year.”

Emanuel did not agree.

“(Americans) will have a full four months to sign up,” Emanuel said. “You can’t prejudge now.”
White House senior adviser Dan Pfeiffer added a new twist to Obama’s pledge to millions of Americans that they could keep their insurance if they like it.

“[People who are happy with their insurance] can keep it, if it hasn’t been changed or canceled,” he said on ABC’s “This Week” with George Stephanopoulos.

In the days that followed the Oct. 1 rollout, the site has been riddled with problems.

The ObamaCare website shut down Saturday night for “extended” repairs, according to the Department of Health and Human Services.

Technicians have shut down HealthCare.gov during weekends since the site launched Oct. 1, but just for a few overnight hours.

"The HealthCare.gov tech team is performing extended maintenance this weekend to improve network infrastructure and make enhancements to the online application and enrollment tools,” agency spokeswoman Joanne Peters said Saturday.

Last week, Health and Human Services Secretary Kathleen Sebelius testified during a congressional hearing that officials are working “24-7” to improve the health insurance website HealthCare.gov. The online portal debuted on Oct. 1 to mostly negative reviews over glitches in the system.

The website was designed to allow people to sign in and sign up for insurance in their state.

It is a part of Obama’s signature health care overhaul. The law, which was passed with no GOP support, was signed by the president in 2010 as a way to fix the nation’s ailing health care system and providing insurance to millions of people who couldn’t afford it.

Sebelius was grilled for three hours last week by lawmakers who wanted to know why there were so many problems with the system. Sebelius took most of the blame for the botched debut.

Jeffrey Zients, a former White House budget deputy, has said the site will be fixed by the end of the month. Sebelius has also said she feels confident about the Nov. 30 re-launch.


Source
.

Monday, November 04, 2013

The Truth About Obamacare


Stefan Molyneux


Published on Oct 24, 2013


Obamacare facts explained by Stefan Molyneux. A comprehensive look at the Patient Protection and Affordable Care Act (PPACA) and it's implementation.

Freedomain Radio is 100% funded by viewers like you. Please support the show by signing up for a monthly subscription or making a one time donation at: http://www.fdrurl.com/donate

Bitcoin Address: 1Fd8RuZqJNG4v56rPD1v6rgYptwnHeJRWs
Litecoin Address: LL76SbNek3dT8bv2APZNhWgNv3nHEzAgKT

Get more from Stefan Molyneux and Freedomain Radio including books, podcasts and other info at: http://www.freedomainradio.com

Amazon US Affiliate Link: www.fdrurl.com/AmazonUS
Amazon Canada Affiliate Link: www.fdrurl.com/AmazonCanada
Amazon UK Affiliate Link: www.fdrurl.com/AmazonUK

Freedomain Radio Facebook: http://www.fdrurl.com/fb
Freedomain Radio Twitter: https://twitter.com/freedomainradio
Freedomain Radio Google+: http://www.fdrurl.com/google
Freedomain Radio LinkedIn: http://www.fdrurl.com/LinkedIn

http://www.weeklystandard.com/blogs/m...

http://www.washingtonpost.com/politic...

http://themattwalshblog.com/2013/10/2...

http://www.forbes.com/sites/theapothe...

http://danfromsquirrelhill.wordpress....

http://news.investors.com/politics-ob...

http://www.newsmax.com/newswidget/oba...

http://reason.com/blog/2013/10/23/the...
.
.

Friday, October 25, 2013

Florida Blue, other health plans cancelling contracts to prepare for new health law rules


By Anna Gorman and Julie Appleby
Kaiser Health News

Published: October 23, 2013

Health plans in Florida and across the country are sending hundreds of thousands of cancellation letters to people who buy their own coverage, frustrating some consumers who want to keep what they have and forcing others to buy more costly policies.

The main reason insurers offer is that the policies fall short of what the Affordable Care Act requires starting Jan. 1. Most are ending policies sold after the law passed in March 2010. At least a few are cancelling plans sold to people with pre-existing medical conditions.

Florida Blue is terminating about 300,000 policies, about 80 percent of its individual policies in the state. Kaiser Permanente in California has sent notices to 160,000 people – about half of its individual business in the state. Insurer Highmark in Pittsburgh is dropping about 20 percent of its individual market customers, while Independence Blue Cross, the major insurer in Philadelphia, is dropping about 45 percent.

An estimated 14 million people purchase their own coverage because they don’t get it through their jobs.

By all accounts, the new policies will offer consumers better coverage, in some cases, for comparable cost, especially after the inclusion of federal subsidies for those who qualify. The law requires policies sold in the individual market to cover 10 “essential” benefits, such as prescription drugs, mental health treatment and maternity care.

In addition, insurers cannot reject people with medical problems or charge them higher prices. The policies must also cap consumers’ annual expenses at levels lower than many plans sold before the new rules.

But the cancellation notices, which began arriving in August, have shocked many consumers in light of President Barack Obama’s promise that people could keep their plans if they liked them.

“I don’t feel like I need to change, but I have to,” said Jeff Learned, a television editor in Los Angeles, who must find a new plan for his teenage daughter, who has a health condition that has required multiple surgeries.

Both Independence and Highmark are cancelling so-called “guaranteed issue” policies, which had been sold to customers who had pre-existing medical conditions when they signed up. Policyholders with regular policies because they did not have health problems will be given an option to extend their coverage through next year.

Consumer advocates say such cancellations raise concerns that companies may be targeting their most costly enrollees.

They may be “doing this as an opportunity to push their populations into the exchange and purge their systems” of policyholders they no longer want, said Jerry Flanagan, an attorney with the advocacy group Consumer Watchdog in California.

Insurers deny that, saying they are encouraging existing customers to re-enroll in their new plans.

“We continue to cover people with all types of health conditions,” said Highmark spokeswoman Kristin Ash.

Some receiving cancellations say it looks like their costs will go up, despite studies projecting that about half of all enrollees will get income-based subsidies.

Kris Malean, 56, lives outside Seattle, and has a health policy that costs $390 a month with a $2,500 deductible and a $10,000 in potential out-of-pocket costs for such things as doctor visits, drug costs or hospital care.

As a replacement, Regence BlueShield is offering her a plan for $79 more a month with a deductible twice as large as what she pays now, but which limits her potential out-of-pocket costs to $6,250 a year, including the deductible.

“My impression was …there would be a lot more choice, driving some of the rates down,” said Malean, who does not believe she is eligible for a subsidy.

Regence spokeswoman Rachelle Cunningham said the new plans offer consumers broader benefits, which “in many cases translate into higher costs.”

“The arithmetic is inescapable,” said Patrick Johnston, chief executive officer of the California Association of Health Plans. Costs must be spread, so while some consumers will see their premiums drop, others will pay more “no matter what people in Washington say.”

Health insurance experts say new prices will vary and much depends on where a person lives, their age and the type of policy they decide to buy. Some, including young people and those with skimpy or high-deductible plans, may see an increase.

Others, including those with health problems or who buy coverage with higher deductibles than they have now, may see lower premiums.

Kaiser Health News (www.kaiserhealthnews.org) is an editorially independent program of the Henry J. Kaiser Family Foundation, a nonprofit, nonpartisan health policy research and communication organization not affiliated with Kaiser Permanente.


Source
.

CBS News reports that the Affordable Healthcare Website gives inaccurate estimates

10.23.2013


CBS NEWS CORRESPONDENT JAN CRAWFORD REPORTS THAT THE AFFORDABLE HEALTHCARE ACT WEBSITE GIVES INACCURATE ESTIMATES TO WOULD-BE CONSUMERS - ON “CBS THIS MORNING”


INDUSTRY ANALYST JONATHAN WU TELLS CRAWFORD THE WEBSITE IS: "INCREDIBLY MISLEADING FOR PEOPLE THAT ARE TRYING TO GET A SENSE OF WHAT THEY'RE PAYING”


CBS News Correspondent Jan Crawford reported that the Affordable Healthcare Act’s website, HealthCare.gov, gives drastically inaccurate estimates of healthcare costs to would-be consumers, in a story that was broadcast today, Oct. 23, 2013 on CBS THIS MORNING (7:00-9:00 AM) on the CBS Television Network.

“Industry executives we talked to literally could not believe that the government is providing these estimates, which they said were useless and could easily mislead consumers,” Crawford told co-hosts Charlie Rose and Norah O’Donnell, adding, “The website repeatedly states that actual prices could be lower but it makes no mention that they could be higher.”

A transcript of the story is below.

JAN CRAWFORD: Norah, Charlie, the administration announced it would provide this new "shop and browse" feature on Sunday, but it's not giving consumers the real picture about the plans that are available... because in some cases people could end up paying double of what they see on the website.

PRESIDENT OBAMA (VIDEO): "The website has not worked as smoothly as it was supposed to..."

As President Obama promises to fix Healthcare.gov, his administration is touting what it calls "improvements" in design—specifically a feature that allows you to "SEE PLANS NOW."

JAY CARNEY (VIDEO): "Americans across the country can type in their zip code and shop and browse."

But CBS News has learned the new "shop and browse" feature often comes with the wrong price tags.

JONATHAN WU: "Incredibly misleading for people that are trying to get a sense of what they're paying."

Industry analysts, like Jonathan Wu, point to how the website lumps people into two broad categories: "49 or under" and "50 or older." Prices for everyone in the 49 or under group are based on what a 27-year-old would pay. In the 50 or older group, prices are based on what a 50-year-old would pay. We ran the numbers for a 48-year-old in Charlotte, N.C.—ineligible for subsidies. According to Healthcare.gov, she would pay $231 a month. The actual plan on Blue Cross Blue Shield of North Carolina's website costs $360—a more than 50 percent increase. The difference: Blue Cross Blue Shield requests your birthday before providing more accurate estimates. The numbers for older Americans are even more striking. A 62-year-old in Charlotte looking for the same plan would get a price estimate on the government website of $394. The actual price is $634. An HHS spokeswoman said it added the "shop and browse" feature to provide "estimates of premiums without tax credits." Chini Krishnan's company helped design California's new health care exchange website. It requires people to enter their birth dates to get a real price quote.

CHINI KRISHNAN: "It is important that the users have a proper trustworthy honest brand experience when they interact with Healthcare.gov and I think providing accurate prices is an integral component of that."

JAN CRAWFORD: Now industry executives we talked to literally could not believe that the government is providing these estimates, which they said were useless and could easily mislead consumers. They also say, Charlie and Norah, that the website repeatedly states that actual prices could be lower but it makes no mention that they could be higher.

Click here to watch the video clip.


Source
.

Monday, May 27, 2013

Archdiocese Pays for Health Plan That Covers Birth Control


By SHARON OTTERMAN
Published: May 26, 2013

The Archdiocese of New York has previously acknowledged that some local Catholic institutions offer health insurance plans that include contraceptive drugs to comply with state law; now, it is also acknowledging that the archdiocese’s own money is used to pay for a union health plan that covers contraception and even abortion for workers at its affiliated nursing homes and clinics.

“We provide the services under protest,” said Joseph Zwilling, a spokesman for the Archdiocese of New York.


.

Monday, April 01, 2013

Christian Institutions Stand up for Religious Liberty


Current Events - Christian Institutions Stand up for Religious Liberty
By

New healthcare policy requires institutions to provide coverage for abortion. A flurry of lawsuits (now up to 45) have been filed against the rule in the Affordable Care Act. These lawsuits claim that forcing employers to pay for abortion-causing drugs violates their freedom and practice of religion, a Constitutional right.

The banner of truth and religious liberty held aloft by the founders of the gospel church and by God’s witnesses during the centuries that have passed since then, has, in this last conflict, been committed to our hands. The responsibility for this great gift rests with those whom God has blessed with a knowledge of His word. We are to receive this word as supreme authority. We are to recognize human government as an ordinance of divine appointment, and teach obedience to it as a sacred duty, within its legitimate sphere. But when its claims conflict with the claims of God, we must obey God rather than men. God’s word must be recognized as above all human legislation. A ‘Thus saith the Lord’ is not to be set aside for a ‘Thus saith the church’ or a ‘Thus saith the state.’ The crown of Christ is to be lifted above the diadems of earthly potentates.” The Acts of the Apostles, 68.

On January 20, 2012 the United States Department of Health and Human Services (HHS), under Secretary Kathleen Sebelius, unveiled a new policy which has come to be known as the “HHS Mandate.”

The new Mandate would require nearly all private health insurance plans to include coverage for all FDA-approved prescription contraceptive drugs and devices, surgical sterilizations and abortion-inducing drugs—drugs that interfere with implantation in the womb and therefore destroy the life of a human being in the earliest stage of development.

The United States Supreme Court has denied a request by a national arts and crafts chain with 500 stores in 42 states, to shield the company from the so-called contraceptive mandate, a part of the Patient Protection and Affordable Care Act, while its legal battle plays out, after a federal court similarly ruled against the Christian-owned company. Its CEO argued that his family would have to either “violate their faith by covering abortion-causing drugs or be exposed to severe penalties.” ww.foxnews.com/politics/2012/12/26.

The American Center for Law and Justice, a pro-life legal organization that focuses on constitutional law, achieved a significant victory in the legal battle against the mandate when a federal appeals court granted an emergency motion for an injunction putting the Department of Health and Human Services (HHS) mandate on hold—preventing it from being enforced against an Illinois business and its owners.

In December 2012, a federal district court in Missouri granted an ACLJ request for an injunction—blocking the mandate from being enforced against a Missouri company. And, in November, a federal appeals court also stepped in and put a halt to the enforcement of the mandate against a St. Louis company.

Following a decision by Supreme Court Justice Sonia Sotomayor denying the arts and crafts chain’s request for an exemption from the administration’s HHS mandate, the Christian retail company said it will defy the mandate. www.lifenews.wpengine.netdna-cdn.com.

An extremely narrow exemption effectively only protects houses of worship. Business owners’ ability to run their businesses consistent with their religious and moral convictions is not protected. Accepting the Administration’s logic would limit the application of religious freedom to individuals acting within their houses of worship on weekends. It would further erode the free exercise of religion, restricting religious believers’ ability to live out their faiths in their day-to-day lives. blog.heritage.org/2012/12/18.


The freedom that has been enjoyed in the United States and protected by the Constitution in the past is being eroded away. 
“Eternal vigilance is the price of liberty.” Wendell Phillips (1811–1884).


,
.

Monday, May 28, 2012

Lloyd’s Of London Preparing For Euro Collapse As Greece Is Warned Of Possible Public Finances Collapse


05/27/2012 ICA

By Andrew Cave, The Telegraph – “Richard Ward said the London market had put in place a contingency plan to switch euro underwriting to multi-currency settlement if Greece abandoned the euro.

In an interview with The Sunday Telegraph he also revealed that Lloyd’s could have to take writedowns on its £58.9bn investment portfolio if the eurozone collapses.

Europe accounts for 18pc of Lloyd’s £23.5bn of gross written premiums, mostly in France, Germany, Spain and Italy. The market also has a fledgling operation in Poland.

Lloyd’s move comes as a major Franco-German provider of credit insurance for eurozone trade, Euler Hermes, said it was considering reducing cover for trade with Greece because of the risk the country might leave the eurozone.

When a company goes bust, it is often sparked by withdrawal of credit insurance for suppliers wanting to trade with it.

A spokesman for Euler Hermes, Bettina Sattler, told Bloomberg: ‘The outcome of the new elections in June remains highly uncertain. Consequently, the situation is further deteriorating. The risk of Greece exiting the eurozone has been revived.

‘In light of the recent developments, Euler Hermes will most probably have to switch to a more prudent approach. [We have] maintained a high level of cover for [our] customers until today. But now we are confronted with a changing situation.’

Lloyd’s fears are likely to be shared by a number of European businesses, which are watching developments in Greece.” Read more.

Greece warned of public finances collapse – “Greece’s public finances could collapse as early as next month, leaving salaries and pensions unpaid unless a stable government emerges from the June 17 election, according to Lucas Papademos, the technocrat prime minister who left office after this month’s inconclusive vote. Mr Papademos warned that conditions were deteriorating faster than expected with cash flow likely to turn negative in early June amid a sharp fall in tax revenues and a loosening of spending controls during two back-to-back election campaigns.” Read more.


Source

.

Sunday, May 27, 2012

Lloyd's 'ready for euro collapse'


The boss of insurance market Lloyd's of London is prepared for a collapse of the euro, it has been reported, and has reduced its exposure to the troubled single-currency region.

Chief executive Richard Ward told the Sunday Telegraph that the London market has put in place a contingency plan to switch euro underwriting to multi-currency settlement if Greece abandons the euro.

Mr Ward has warned that the Lloyd's market, which is made up of around 80 insurance syndicates, could have to take writedowns on its £58.9 billion investment portfolio if the eurozone collapses.

Europe accounts for 18% of Lloyd's £23.5 billion of gross written premiums, mostly in France, Germany, Spain and Italy. The market also has a fledgling operation in Poland.

Mr Ward told the Sunday Telegraph: "I'm quite worried about Europe. With all the concerns around the eurozone at the moment, we've got to be careful doing business in Europe and there are a lot of question marks over writing business in the future in euros."

Mr Ward said Lloyd's had been working hard on contingency planning and had the capability to switch settlement of European underwriting from euros to other currencies.

The contingency planning comes as German politicians piled the pressure on Greece ahead of elections on June 17.

The country's crisis deepened earlier this month after leaders failed to form a coalition government.

If an anti-austerity party is elected in June, many fear Greece will be denied further tranches of bailout cash and the country will have to exit the euro.


SOURCE


Wednesday, April 04, 2012

Conscience concerns could prove decisive in health care ruling

The current U.S. Supreme Court Justices. Courtesy of the U.S. Supreme Court.


By Benjamin Mann

Washington D.C., Mar 29, 2012 / 04:51 pm (CNA/EWTN News).- Inadequate conscience protections may lead the Supreme Court to reject the 2010 health care law, a Jesuit priest and legal scholar predicted after three days of arguments in the historic case.

“I think there are sufficient problems with the bill, as passed, that the justices could say: 'This is unconstitutional,'” Father Robert J. Araujo, S.J., told CNA on March 29.

“There are certainly those problems that have been in the news, and I think there are some other ones. For example – the question of conscience, and conscience protection.”

“This is a very complicated law, and the more we examine it, we see more problems and concerns,” noted Fr. Araujo, who holds the John Courtney Murray Professorship at the Loyola University Chicago School of Law.

“I tend to think that's on the minds of the lawyers and the justices: 'Are we going to see more litigation, if we don't resolve these conscience-protection and other issues?'”

“That's why I see an opportunity for the court to say: 'Look, there are some serious problems with this legislation. Congress has done a lot of work, (but) it's their responsibility to write a law that will pass constitutional muster and judicial review.”

The court's March 26-28 period of questioning focused on the law's “individual mandate,” which requires virtually all citizens to obtain health insurance.

Most observers believe the law's fate will hinge upon whether the requirement is judged to be a means of regulating interstate commerce – as the Obama administration maintains – or an unconstitutional overtaking of states' power by the federal government.

Fr. Araujo thinks the law is unlikely to be upheld either fully or in part.

“Having followed the arguments and the questions, I don't think the likelihood of a complete vindication is very strong,” the Loyola University professor predicted on March 29.

He also has doubts about the law being upheld with some portions removed – because legislators did not include a “severability” provision that would allow some parts to stand if others, such as the individual mandate, were struck down.

Although the main issue before the court is the individual insurance mandate, the Jesuit professor thinks other aspects of the law will factor into the court's decision as well – including the widely-criticized contraception and sterilization mandate, a federal rule made as part of the health care law's implementation.

The Supreme Court justices, he said, realize that there are constitutional concerns surrounding “who exactly is going to be paying for what” under the law, and “how that might affect their own moral concerns, which are constitutionally protected.”

If the law is upheld, the justices could reasonably expect challenges to continue on different constitutional grounds – including the free exercise of religion, a factor in eight states' current lawsuits against the law's contraception mandate.

The result could be “a repetition of what we've seen so far,” with various lawsuits advancing in federal court seeking “review of the legality of certain provisions” in the health care law.

“There are lots of concerns with this legislation,” Fr. Araujo said. “Do we want to have another 'go-around' in the not-too-distant future, on other elements?”

Health care, the priest and professor noted, is a pressing issue that seriously affects millions of people.

But the Obama administration, he suggested, should not have attempted to solve it in a manner that was both constitutionally questionable and morally provocative.

Although the Church regards health care as a right that should be secured for all members of society, opinions differ as to how this should be achieved in practice. The Catholic notion of “subsidiarity” requires that problems be solved by the lowest level of competent authority.

Some Catholic critics of the health care law have invoked this concept as a criticism of the federal health care reform, which they say could have been better handled by the individual states.

“I think in its own way, the U.S. Constitution – under the Tenth Amendment – in part addresses this important concept of subsidiarity,” Fr. Araujo said, citing the provision by which the powers not given to the federal government by the constitution “are reserved to the states respectively, or to the people.”

“What might be proper for Florida may not work in California,” the Loyola University professor noted. “The states do have a proper, lawful role in determining what is good and what is not for their citizenry. That's how I see the subsidiarity rule playing out in the U.S. Constitution.”

“The program Massachusetts legislated a few years ago is not without its problems or faults,” Fr. Araujo observed, recalling legislation signed by then-Governor Mitt Romney. “But the state was addressing the issue of health care for its citizens.”

CNA also spoke on March 29 with Professor Michael Scaperlanda, who teaches at the University of Oklahoma and contributes to the Catholic law blog “Mirror of Justice.”

Scaperlanda has criticized the federal government's individual insurance mandate as unconstitutional. On Thursday, however, he held off from making any predictions as to whether the health care law would be upheld in part or in full by the Supreme Court.

But he noted that there were good reasons for Catholics to prefer state-level solutions to the problem of securing health care for all.

At the state level, he noted, a requirement for individuals to purchase insurance could be squared with both the Constitution and Catholic social teaching.

If the federal health care law is overturned, Scaperlanda is hopeful that solutions for the uninsured, and those with preexisting conditions, can be found at a lower level of authority.

“One reason would be, that our state legislators are much more accessible to us than our federal legislators,” he explained.

“I'm Facebook friends with several of my state legislators; I can have conversations with them. They're much more in tune to the values of people in the community than people in Washington.”

Similarly, individual states would have greater freedom to experiment to see which policies best solve the complex problems of health care reform. Other states could adopt policies that are shown to work, and more local control would make it easier to change those that do not achieve results.

“Multiple heads are better than one,” Scaperlanda said.

“Having different proposals and solutions, and watching to see what works, leads to a better solution than having a small group of policy experts tell us what's going to work and then hoping for the best.”


Thursday, March 18, 2010

The text of President Barack Obama's speech in Strongsville


By Amanda Garrett, Sun News
March 15, 2010, 1:30PM


STRONGSVILLE -- Here is the complete text of President Barack Obama's remarks at the Ehrnfelt Recreation Center.

"Hello, Ohio! It’s great to be here in the Buckeye State. And it’s even better to be out of Washington for a little while.

"I want to thank Connie and her family for being here on behalf of Natoma. It’s not easy to share such a personal story. I appreciate your willingness to do so. I want you to know that she is the reason that I am here today. I know that she felt it was important that her story be told.

"Last month, I read a letter from Natoma. She’s self-employed, trying to make ends meet, and has for years done the responsible thing: buying health insurance through the individual market. The thing is, sixteen years ago, she was diagnosed with a form of treatable cancer. And even though she had been cancer free for more than a decade, the insurance company kept jacking up her rates anyway, year after year. So she increased her out-of-pocket expenses. She raised her deductible. She was doing everything she could to maintain health insurance that would be there for her in case she got sick.

"But even as she upped her deductible to the maximum, last year Natoma’s insurance company raised her premiums by more than 25 percent. Over the past year, she paid more than $6,000 in monthly premiums. She paid more than $4,000 out-of-pocket for co-pays, medical care, and prescriptions. So she ponied up more than $10,000 dollars. But because she never hit her deductible, her insurer only spent $900 on her care. And yet what comes in the mail at the end of last year? A letter telling Natoma that her premiums would go up again by more than 40 percent.

"She just could not afford it. She didn’t have the money. And despite her desire to keep her coverage – despite her fears that she would get sick and lose the home her parents built – she finally surrendered and gave up her health insurance. January was her last month of being insured. Like so many responsible Americans – folks who work hard every day, who try to do the right thing – she was forced to hang her fortunes on chance. She hoped against hope she would stay healthy. She feared terribly she would not.

"That was the letter. And I understand Natoma was pretty surprised when she found out that I read it – word for word – to the CEOs of America’s largest insurance companies – including the company that hiked up her rates by more than 40 percent.

"This was less than two weeks ago. But then Natoma’s worst fears were realized. Just last week, she was working on a nearby farm, walking outside – apparently, chasing after a cow – when she collapsed. She was rushed to the hospital. She was very sick. She needed two blood transfusions. Doctors performed a battery of tests. And on Saturday, Natoma was diagnosed with leukemia – a serious form of cancer.

"The reason Natoma is not here today is that she’s lying in a hospital bed, suddenly faced with this emergency – suddenly thrust into a fight for her life. She expects to face a month or more of aggressive chemotherapy.

"And she is racked with worry not only about her illness but about the cost of the tests and treatments she will surely need to beat it.

"I’m here because of Natoma.

"I’m here because of countless others who have been forced to face the hardest and most terrifying challenges in their lives with the added burden of medical bills they cannot pay.

"I’m here because I remember my own mother, in the last six months of her life, on the phone in her hospital room arguing with insurance companies when she should have been spending time with her family.

"I’m here because of the millions denied coverage because of pre-existing conditions – or dropped from coverage when they get sick.

"I’m here because of the small businesses forced to choose between health care and hiring.

"I’m here because of the seniors unable to afford the prescriptions they need.

"I’m here because of the folks seeing premiums going up by thirty, forty, fifty percent in a year.

"I am here because this is not the America I believe in – and it’s not the America you believe in.

"And so when you hear people say “start over” – I want you to think of Natoma. When you hear people saying that this isn’t the “right time” – think of what she’s going through. When you hear people talk about who’s up and who’s down in the polls – instead of what’s right or what’s wrong for the country – think of her and the millions of responsible people – working people – being hurt by today’s system of health insurance. And I want you to remember: There but for the grace of God go I.

"This status quo on health care is simply unsustainable. We cannot have a system that works better for the insurance companies than it does for the American people. We know what will happen if we fail to act. We know our government will be plunged deeper into debt. We know millions more people will lose coverage. And we know that rising costs will saddle millions more families with unaffordable expenses – and will force many small businesses to drop coverage altogether. A study just came out yesterday – a non-partisan study – which found that without reform, premiums could more than double for individuals and families over the next decade. Family policies could pass $25,000. Can you afford that?

"We have debated health care in Washington for more than a year. Every proposal has been put on the table. Every argument has been made. I know many people view this as a partisan issue, but both parties have found plenty of areas where we agree. And what we’ve ended up with is a proposal that’s somewhere in the middle – one that incorporates the best ideas from Democrats and Republicans.

"On one side of the spectrum, there were those who wanted to scrap our system of private insurance and replace it with government-run health care. But I didn’t think that was practical or realistic.

"On the other side of the spectrum, there are those who believe the answer is to simply unleash the insurance industry, by providing less oversight and fewer rules. I call this the “putting the foxes in charge of the hen house” approach. It would only give insurance companies more leeway to raise premiums and deny care.

"I don’t believe we should give the government or the insurance companies more control over health care in America. I believe it’s time to give you – the American people – more control over your own health insurance.

"That’s why my proposal builds on the current system where most Americans get their health insurance from their employer. If you like your plan, you can keep your plan. If you like your doctor, you can keep your doctor. I wouldn’t want any plan that interferes with the relationship between a family and their doctor.

"Essentially, my proposal would change three things about the current health care system. First, it would end the worst practices of insurance companies. Within the first year of signing health care reform, thousands of uninsured Americans with pre-existing conditions will be able to purchase health insurance for the first time in their lives. This year, insurance companies will be banned forever from denying coverage to children with pre-existing conditions. This year, they will be banned from dropping your coverage when you get sick. Those practices will end.

"If this reform becomes law, all new insurance plans will be required to offer free preventive care to their customers starting this year – free check-ups so we can start catching preventable illnesses on the front end. Starting this year, if you buy a new plan, there will be no more lifetime or restrictive annual limits on the amount of care you receive from your insurance companies. And if you’re an uninsured young adult, you’ll be able to stay on your parents’ policy until you’re 26 years old.

"The second thing that would change about the current system is this: for the first time, uninsured individuals and small businesses will have the same kind of choice of private health insurance that Members of Congress get for themselves. If this reform becomes law, Members of Congress will be getting their insurance from the same place the uninsured get theirs. Because if it’s good enough for the American people, it ought to be good enough for the people you send to Washington.

"My proposal also says that if you still can’t afford the insurance in this new marketplace, we will offer you tax credits to do so – tax credits that add up to the largest middle class tax cut for health care in history. After all, the wealthiest among us can already buy the best insurance there is, and the least well-off are able to get coverage through Medicaid. But it’s the middle-class that gets squeezed, and that’s who we have to help.

"Now, it’s true that all of this will cost money – about $100 billion per year. But most of this comes from the nearly $2.5 trillion a year that America already spends on health care. It’s just that right now, a lot of that money is being spent badly. With this plan, we’re going to make sure the dollars we spend go toward making insurance more affordable and more secure. We’re also going to eliminate wasteful taxpayer subsidies that currently go to insurance companies. And we will set a new fee on insurance companies that stand to gain as millions of Americans are able to buy insurance. Here’s the point: our proposal is paid for.

"Finally, my proposal would bring down the cost of health care for families, businesses, and the federal government. Americans buying comparable coverage to what they have today in the individual market would see premiums fall by 14 to 20 percent. For Americans who get their insurance through the workplace, costs could fall by as much as $3,000 a person. By now, we have incorporated most of the serious ideas from across the political spectrum about how to contain the rising cost of health care – ideas that go after the waste and abuse in our system, especially in programs like Medicare. Our cost-cutting measures would reduce most people’s premiums and bring down our deficit by up to $1 trillion over the next two decades. And those aren’t my numbers; they are the savings determined by the Congressional Budget Office, the nonpartisan, independent referee of Congress.

"Now, the opponents of reform have tried a lot of different arguments to stop these changes. But maybe the most insidious is the idea that somehow this would hurt Medicare. And I know we’ve got some seniors with us today. So let me just tell you directly: this proposal adds almost a decade of solvency to Medicare. This proposal would close that gap in prescription drug coverage – called the doughnut hole – that sticks seniors with thousands of dollars in drug costs. This proposal will over time help to reduce the costs of Medicare that you pay every month. And this proposal would make preventive care free so you don’t have to pay out-of-pocket for tests that keep you healthy.

"Yes, we are going after the waste, fraud, and abuse in Medicare. But that’s because these are dollars that should be spent on care for seniors, not the care and feeding of insurance companies through subsidies and sweetheart deals. Every senior should know: there is no cutting of your guaranteed Medicare benefits. Period. This proposal makes Medicare stronger, makes the coverage better, and makes its finances more secure. Anyone who says otherwise is misinformed – or is trying to misinform you.

"So that’s the proposal. And I believe Congress owes the American people a final up-or-down vote. Of course, now that we’re approaching this vote, we’re hearing a lot of people in Washington talking about the politics. Talking about what this means for November. Talking about the poll numbers for the Democrats and the Republicans. But that’s why I wanted to come here today.

"Because in the end, this debate is about far more than the politics. It's about what kind of country we want to be. It’s about the millions of lives that would be touched and, in some cases, saved by making private health insurance more secure and more affordable. It’s about a woman, lying in a hospital bed, who wants nothing more than to be able to pay for the care she needs.

"And the truth is, what is at stake in this debate is not just our ability to solve this problem, but our ability to solve any problem. The American people want to know if it's still possible for Washington to look out for their interests and their future. They are waiting for us to act. They are waiting for us to lead. And as long as I hold this office, I intend to provide that leadership. I don’t know about the politics. But I know what’s right. So I am calling on Congress to pass these reforms – and I look forward to signing them into law.

"Thank you, God bless you, and God bless the United States of America."

.
.
.

Sunday, February 28, 2010

Sen. Jay Rockefeller: "the shark that sits right below the water"...


Sound Bites
2010

Sen. Jay Rockefeller (D., WV), Health care summit, 2-25-2010, Health Insurance Industry is a shark beneath the water (:11)

The health insurance industry is the shark that sits right below the water and you don’t see that shark until you feel the teeth of that shark.


P.S.

What a great analogy for the sharks that swim below the water, with the teeth, etc?

Could Jay Rockerfeller fit that same description of a prehistoric sea predator swiming in the midst of an unsuspecting public? With the rows of teeth to boot? What a way to swim?
Is someone projecting, here?

The U.S. Senate:
A millionaire's dream... Where men get paid for doing nothing, but talking.

.A millionaire's This is like a Starkist commercial!dSorry, Charlie.
.ream

Thursday, January 07, 2010

C-SPAN Calls for More Transparent Health Care Talks

January 5, 2010 2:25 PM

Posted by Stephanie Condon


(AP)


As a presidential candidate, Barack Obama called for completely transparent health care deliberations and even promised to hold all negotiations on C-SPAN. Now, as the health care debate reaches its final stages, the nonprofit cable company is asking Washington leaders to follow through on that promise.

C-SPAN CEO Brian Lamb sent a letter to congressional leaders last week, asking that they "open all important negotiations, including any conference committee meetings, to electronic media coverage."

"Many of your rank-and-file members, and the nation's editorial pages have all talked about the value of transparent discussions on reforming the nation's health care system," , Lamb said in the letter, which was sent to House Speaker Nancy Pelosi (D-Calif.), House Minority Leader John Boehner (R-Ohio), Sen. Majority Leader Harry Reid (D-Nev.) and Sen. Minority Leader Mitch McConnell (R-Ky.). "Now that the process moves to the critical stage of reconciliation between the Chambers, we respectfully request that you allow the public full access, through television, to legislation that will affect the lives of every single American."

As Lamb notes, "literall hundreds of hours" of committee hearings, debate and meetings have been broadcast on C-SPAN through the health care debate, allowing journalists, bloggers, watchdog groups and citizens to follow the process. Other significant parts of the health care debate, however, have remained behind closed doors, such as Mr. Obama's negotiations with the pharmaceutical industry which resulted in a deal committing the industry to a specific contribution to reform.

CBSNews.com Special Report: Health Care

Now that Democrats have passed a health care bill in both the House and the Senate, they will need to reconcile the two bills. That process could take place through the formal "conference committee" process, or it could happen informally. Either way, there are sure to be important negotiations and meetings taking place among Democratic leaders that remain private.

Lamb said the C-SPAN networks are willing to commit all of the resources necessary to comprehensively cover the upcoming conference committee sessions live.

"We are most willing to employ the latest digital technology to make the cameras, lights and microphones as unobtrusive as possible," he added.

When asked last week about the level of transparency so far in the health care debate, White House Press Secretary Robert Gibbs said the legislative process has played out clearly in the hearings and debates that have been aired on C-SPAN.

"I think, quite frankly, people have a pretty good sense of who is battling on behalf of thousands of lobbyists that are trying to protect drugs profits and insurance profits, and who's fighting on behalf of middle-class Americans," he said.

Pressed on the issue again today, Gibbs said he has not seen the C-SPAN letter but that he doesn't think "the American people have lacked for information on what's in these bills," or "the political and policy arguments around people's position."
.
.

Wednesday, January 06, 2010

Obama, Dems Agree to Closed-Door Health Negotiations

Updated January 06, 2010

FOXNews.com

President Obama and congressional Democrats head into another strategy session Wednesday over health care reform after deciding Tuesday night to keep the final negotiations as GOP-free as possible by bypassing the traditional conference committee process.


Jan. 5: Rep. Chris Van Hollen and House Speaker Nancy Pelosi speak at a news conference to discuss health care legislation. (AP Photo)


President Obama and congressional Democrats head into another strategy session Wednesday over health care reform after deciding Tuesday night to keep the final negotiations as GOP-free as possible by bypassing the traditional conference committee process.

The White House and Democratic leaders in Congress decided to keep the last leg of talks a closed-door affair. They concluded that the House will work off the Senate's version, amend it and send it back to the Senate for final passage, according to a House leadership aide, speaking on condition of anonymity in order to discuss the private meeting.

The move streamlines the process to avoid Republican efforts to slow it down.

But Republicans aren't giving up yet. House Minority Whip Eric Cantor, R-Va., on Wednesday released a list of 37 House Democrats he claims can be persuaded to vote against the final bill. Cantor noted that Democrats can't afford to lose one of the 60-vote coalition they assembled in the Senate and can't afford to lose more than two of the 220 votes they assembled on the House side.

"I still believe there is an opportunity to prevent this bill -- a bill that will fundamentally alter the relationship between patients and doctors, harm seniors, and impose massive taxes and mandates on small businesses -- from becoming law," he wrote. "If we can convince enough of these 37 members (along with the 39 Democrats who already voted no) to reconsider and switch their position on the bill, I know that we can defeat this government take-over of our health care before it becomes law."


Cantor listed House Democrats who are known to have anti-abortion views as well as Democrats who represent a lot of seniors enrolled in Medicare Advantage. The Republican argued that proposed cuts to Medicare Advantage and potentially "weakened" language on restrictions for abortion funding could put those Democrats in play.

Obama is expected to meet with top House Democrats Wednesday afternoon, as they craft strategy well before Congress returns. The aim is to get a final bill to Obama's desk before the State of the Union policy address sometime in early February.

Democrats reacted defensively to criticism that they are taking the final, most crucial stage of the debate behind closed doors, contending they've conducted a transparent process with hundreds of public meetings and legislation posted online. Republicans seized on a newly released letter from the head of the C-SPAN network calling on congressional leaders to open the final talks to the public, and cited Obama's campaign trail pledge to do just that.

Asked about that promise, House Speaker Nancy Pelosi remarked, without elaboration: "There are a number of things he was for on the campaign trail."

Facing the need to maintain a tenuous 60-vote coalition in the Senate, House Democrats likely will have to give up on starting a new government insurance plan to compete with the private market, something that's a nonstarter with Senate moderates. In its place they hope for more generous subsidies for lower-income families to buy health insurance.

Obama agreed at Tuesday evening's meeting to help strengthen affordability measures beyond what's in the Senate bill, the aide said.

Pelosi suggested Tuesday that House members wouldn't insist on the government plan as long as the final bill provides "affordability for the middle class, accountability for the insurance companies ... accessibility by lowering cost at every stage."

"There are other ways to do that, and we look forward to having those discussions," she said.
House Democrats want the Senate to agree to language revoking insurers' antitrust exemption as a way to hold insurance companies accountable in absence of direct government competition, said Rep. Chris Van Hollen, a member of the House leadership.

The bills passed by the House and Senate both would require nearly all Americans to get health insurance coverage and would provide subsidies for many who can't afford the cost, but they differ on hundreds of details. Among them are whom to tax, how many people to cover, how to restrict taxpayer funding for abortion and whether illegal immigrants should be allowed to buy coverage in the new markets with their own money.

Concerns about affordability are paramount. Major subsidies under the bills wouldn't start flowing to consumers until 2013 at the earliest. Even with federal aid, many families still would face substantial costs.

The House bill would provide $602 billion in subsidies from 2013-2019, covering an additional 36 million people.

The Senate bill would start the aid a year later, providing $436 billion in subsidies from 2014-2019, and reducing the number of uninsured by 31 million.

"Affordability is a critical issue," Van Hollen said.

But sweetening the deal for low- and middle-income households could require more taxes to pay for additional subsidies. And the House and Senate are also at odds over whom to tax. The House wants to raise income taxes on individuals making more than $500,000 and couples over $1 million. The Senate would slap a new tax on high-cost insurance plans. Although the Obama administration supports the Senate's insurance tax as a cost-saver, labor unions, which contribute heavily to Democratic candidates, are against it.

The House may end up accepting the insurance tax if it hits fewer people than the Senate's design now calls for. There also could be common ground in a Senate proposal to raise Medicare payroll taxes on individuals making more than $200,000 and married couples over $250,000.

The Associated Press contributed to this report.


.

Saturday, November 28, 2009

Senate health care bill creates new marriage penalty


Proposal packed with 17 new levies


By Stephen Dinan and David M. Dickson THE WASHINGTON TIMES

Senate Democrats' health care bill would create a new marriage penalty by imposing a tax on individuals who make $200,000 annually but hitting married couples making just $50,000 more.

That's one of 17 new taxes imposed by the bill, which also creates a levy on elective plastic surgery - some call it "botax" - and places a 40 percent excise tax on those who have generous health care plans.

"If you have insurance, you get taxed. If you don't have insurance, you get taxed. If you need a life-saving medical device, you get taxed. If you need prescription medicines, you get taxed," said Senate Minority Leader Mitch McConnell, Kentucky Republican, who is leading the fight against the bill.

The new taxes would be used to fund an expansion of government medical programs and to fund subsidies for lower-income individuals to buy insurance, extending health care coverage to 94 percent of eligible non-elderly Americans.

Democrats said the bill will offer lower health care costs for small businesses and families, and said the new taxes are aimed at upper-income earners, so costs would not go up for the middle class. They said that makes good on President Obama's campaign pledge not to increase taxes on families making less than $250,000 a year, which explains the reason for the new marriage penalty.

"We wanted to make this provision consistent with the president's pledge not to increase taxes on singles making under $200,000 and married couples making under $250,000," said Jim Manley, a spokesman for Senate Majority Leader Harry Reid, who wrote the Senate bill.

"Yes, this structure can create a 'marriage penalty' for some couples. It also creates a 'marriage bonus' for others," he said. "A married couple with one wage earner can earn up to $250,000 without facing this higher tax, whereas a single person in the same job with the same pay would be hit by it."

But a married couple in which each earner makes $150,000 would be hit with the tax, whereas an unmarried couple living together with the same incomes would not.

Ryan Ellis, tax policy director at Americans for Tax Reform, said the new marriage penalty comes on top of an existing one that's always been part of the payroll tax, which funds Social Security and Medicare.

He said when the payroll tax was created to fund Social Security during the New Deal, lawmakers didn't anticipate the freelance of two-income families, so there's always been a sort of marriage penalty for couples whose incomes topped the single-earner income taxation level.


Such penalties have been thorny issues in the tax codes for years.

The new tax would rise from 1.45 percent to 1.95 percent for singles making $200,000 a year and couples making $250,000.

Congress earlier this decade tried to reduce the marriage penalty in the income tax code by adjusting the standard deduction for single taxpayers and married couples and expanding the 15 percent tax bracket for couples filing joint tax returns.

Mr. Ellis said another problem with Democrats' plan is that the new payroll tax is not indexed for inflation, even though wage growth is about 5 percent a year. That means the tax will capture an ever-larger share of taxpayers.

"Fifteen years from now, someone who today is earning $100,000, if their wage growth just grows on average, 15 years from now they're going to be paying this tax," Mr. Ellis said.

The plastic surgery tax could increase the cost of nips and tucks by imposing a 5 percent tax on the cost of such surgeries. The tax is slated to go into effect Jan. 1 and is expected to raise $5.8 billion over 10 years. It would cover all elective procedures, whether covered by insurance or not, but would not be levied on surgeries intended to repair personal injuries.

Some of the taxes are already running into political trouble with Democrats' core supporters.

The Teamsters union on Thursday blasted the proposal to impose a 40 percent excise tax on "Cadillac" high-value health insurance plans, saying it would threaten the benefit-rich coverage unions have fought hard to win for their workers.

"Any claim that it affects only 'Cadillac' plans and thus the wealthy is misleading," said Teamsters President James P. Hoffa Jr. "This tax will fall on one-third of Americans in 10 years. ... The idea that this tax will curtail rising premiums is just dead wrong."

The tax is slated to go into effect in 2013 and would apply to individual policies worth $8,500 or family policies worth $23,000. A slightly higher threshold would apply for early retirees and those in high-risk professions.

Budget analysts said they expect that employers and consumers will start to ditch the high-value plans and instead pay the money to workers in higher wages and salaries, so most of the nearly $150 billion in revenue on which Democrats are counting from the provision would come from higher income taxes.

"Put a tax on my high-premium health plan and suddenly it's not such a good deal," said Roberton Williams, a senior fellow at the Tax Policy Center. "I'd rather have the cash."

Several relatively small tax increases will be aimed at health savings accounts and medical savings accounts. One will change the definitions for medical expenses that qualify as itemized deductions. Another will raise the penalties for withdrawing funds from these vehicles. A third would limit health-related flexible spending arrangements.

"All of these changes are designed to make health savings accounts less attractive and cripple consumer-directed health care plans," said Michael Cannon, director of Health Policy Studies at the Cato Institute. Altogether, they would raise about $20 billion through 2019.

Jennifer Haberkorn and S.A. Miller contributed to this report.


Source: http://washingtontimes.com/news/2009/nov/20/married-couples-face-tax-in-senate-health-care-bil/
.